
Introduction
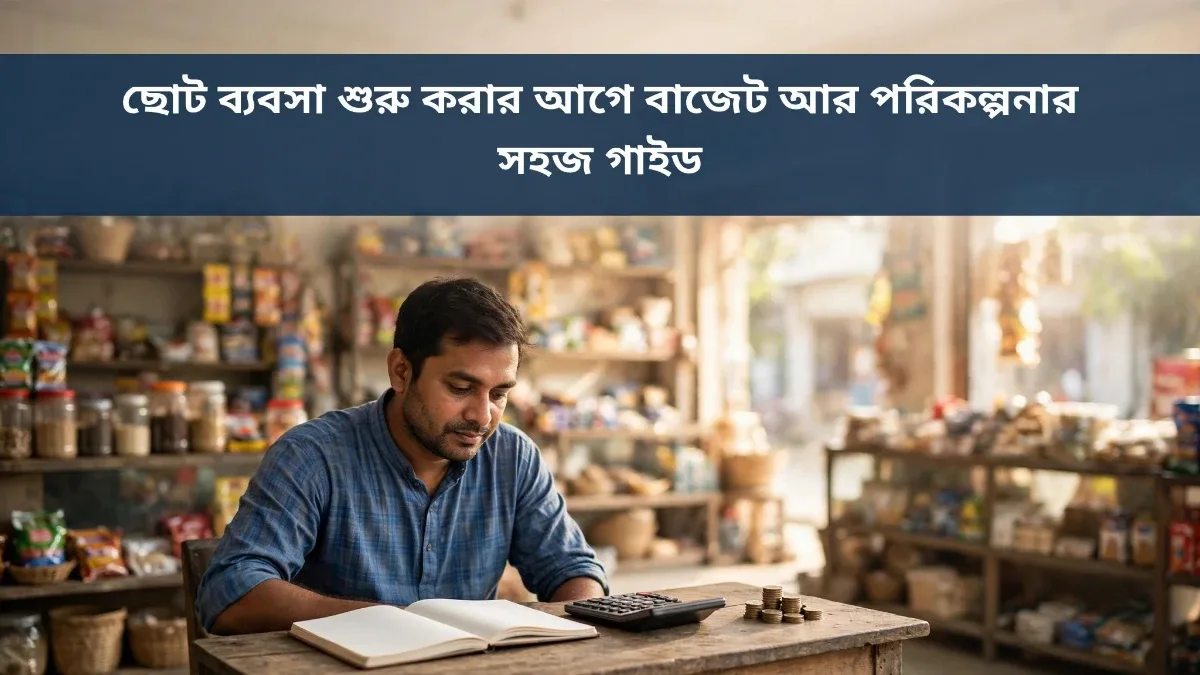
Many people dream of starting their own small business. Whether alongside a day job or as a full-time venture, launching without a solid plan often leads to early stumbles. Running out of capital, losing track of expenses, or struggling to find customers—most of these setbacks stem from a lack of planning. Here is a straightforward guide to setting up your budget and plan before you launch a small business.
1. Validate Your Business Idea Thoroughly
Before you begin, ask yourself whether there is real demand for what you want to sell. Pay attention to what people in your area are looking for and willing to buy. Talk to acquaintances, explore local markets, and research online. A business cannot survive on passion alone—sales only happen when there is genuine demand. Pouring money into an unvalidated idea significantly increases your risk of loss.
2. Define Your Target Customers
Not everyone is your customer. Be clear about who your product or service is designed for. Whether you are targeting students, office workers, homemakers, or business owners, your pricing and marketing approach will vary based on their age, income, and needs. Knowing your target audience helps you spend less on advertising while driving more sales. Take the time to build a clear picture of your ideal customer right from the start.
3. List Every Expected Expense
Write down every anticipated business cost. Shop rent, inventory purchases, equipment, transportation, packaging, mobile bills, and marketing—do not leave out even the smallest expenses. Many new owners only calculate major costs, only to watch small recurring expenses push them over budget later. A complete list gives you a clear view of how much money you truly need.
4. Separate Startup Costs from Operating Costs
Every business has two types of expenses. Startup costs are one-time outlays, such as setting up a shop, obtaining licenses, or buying equipment. Operating costs are recurring monthly expenses, such as rent, salaries, restocking inventory, and electricity bills. Separating the two helps you see how much you need to launch and how much you need each month to stay afloat, reducing the risk of running out of cash and shutting down unexpectedly.
5. Set Aside an Emergency Fund
It is completely normal for revenue to be low during the first few months. Building a customer base takes time, so it is unrealistic to expect immediate profits. Set aside an emergency fund equal to at least three to six months of operating expenses. Do not touch this reserve for routine spending—keep it strictly for unexpected emergencies. A solid emergency fund helps your business survive tough patches.
6. Secure Your Funding Sources in Advance
Decide upfront where your startup capital will come from. Personal savings, family support, a bank loan, or a business partnership—each option has its own pros and cons. If you take out a loan, calculate the installments and interest ahead of time to ensure your monthly revenue can cover the repayments. Instead of relying on scattered sources, stick to one clear funding plan.
7. Calculate Your Profit Margins Early
Figure out how much profit you will earn on each item before you start selling. Add up the purchase price, shipping, packaging, and other overhead to find your total unit cost, then set your selling price. Price too high and you will lose customers; price too low and you will not make a profit. Compare your rates with nearby competitors to set a fair price. Clear profit math tells you early on whether the business is viable.
8. Organize Your Essential Paperwork
Even a small business requires proper documentation. Keep your trade license, tax records, bank account details, and transaction receipts organized from day one. Having your legal paperwork in order prevents future headaches and makes it easier to qualify for bank loans later. Investing a little time at the start saves you from major trouble down the road.
9. Start Small and Scale Gradually
Opening a large store or stocking too many products right away is risky. Start on a small scale, observe customer feedback, and see which items sell best. Once you begin turning a steady profit, expand step by step. Losses from a small launch are manageable, whereas a single misstep in an oversized launch can wipe out your entire capital.
10. Record Your Daily Accounts Consistently
Log all daily income and expenses in a ledger or a mobile app. Without tracking daily sales, costs, and net profit, it is impossible to tell whether your business is actually making or losing money. Review your numbers once a week to spot where you are overspending. Consistent bookkeeping catches mistakes early and makes decision-making much easier.
Final Thoughts
Starting a small business is not overly difficult, but jumping in without a proper budget and plan is unwise. Validating your idea, defining your audience, tracking expenses, and maintaining an emergency fund will greatly improve your odds of long-term survival. Avoid rushing—start small and grow steadily. With the right plan, even a modest business can achieve lasting success.
Discussion & Comments (0)
No comments on this post yet. Be the first to comment!